

Piere: Budget, Plan, Save

- 188.00 Reviews
- 4.5
- Downloads
- 50,000+
Our take on Piere: Budget, Plan, Save from Appgk
Managing money often looks easy until several accounts, bills, subscriptions, and irregular expenses start competing for attention. I found Piere: Budget, Plan, Save most useful when I treated it as a planning tool rather than a magic fix for spending. Its purpose is to bring budgeting and saving into one routine, helping me see what my money is meant to do before the month gets away from me.
That focus makes it appealing for anyone who wants more structure without building a complicated spreadsheet. At the same time, the first experience can involve more checking and patience than the short store description suggests. Financial apps depend on accurate account connections and current information, so a confusing balance is not always caused by the app itself. My review therefore focuses on the practical side: where I would expect a new user to hesitate, how I would set it up carefully, and what I would do when the workflow stops looking right.
Getting comfortable with the budgeting workflow
Piere: Budget, Plan, Save is a finance app from UniversTech, and I see its strongest role as a central place for everyday money decisions. Instead of checking a bank account only after spending has happened, I would use it to decide how much is available for essentials, flexible purchases, and savings. That distinction matters. A budgeting app is most helpful before I tap “buy,” not just when I am reviewing a list of old transactions.
The app is free to download and is rated for Everyone, which makes it approachable for households that want to start with basic planning. It has passed the early-adopter stage too, with more than fifty thousand installs and an average rating of four and a half from hundreds of ratings. I would still avoid treating those figures as a guarantee that every bank connection or personal setup will behave identically. Finance tools are especially sensitive to account type, login security, and how each institution shares information.
Best Parts of Piere: Budget, Plan, Save
Things to Keep in Mind About Piere: Budget, Plan, Save
The first place users may get stuck is the difference between seeing money and understanding available money. A current account balance can include payments that have not fully cleared, scheduled bills, or recent purchases that need categorizing. If I looked only at the largest number on screen, I could easily assume I had more spending room than I really did. My practical approach would be to compare the app’s picture with the bank’s own recent activity before making a major decision.
I would also resist trying to perfect every category on the first day. The useful starting point is a short list of the expenses that control the month: housing, utilities, transport, groceries, debt payments, and savings. Once those are sensible, smaller categories can be refined gradually. This keeps the setup from turning into an accounting project and makes it easier to notice whether the plan reflects real life.
News and Features Related to Piere: Budget, Plan, Save

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Checks I would make before relying on the plan
Before connecting anything, I would make sure I am using the current version, which is 6.2.2, and that the device meets the minimum operating system requirement of version 10. That simple check prevents a surprising amount of wasted troubleshooting. I would also install the app through the normal official store route and keep my banking credentials out of notes, messages, or screenshots.
After adding an account, I would compare several visible details rather than checking only one balance. I would look at the latest transaction, the account name, and the direction of the balance. If one of those looks wrong, I would pause before creating a detailed savings plan. A mismatch at this stage can make every later category feel unreliable.
Don't want to read the full review?
Another useful check is timing. Financial information does not always update at the exact moment a card payment is made. If a purchase is missing, duplicated, or still appears pending, I would first give the connection time and compare it with the institution’s own app. Repeatedly reconnecting while a transaction is still processing can make the situation harder to understand rather than fixing it.
I would then create a deliberately modest first budget. Instead of assigning every penny immediately, I would use the initial plan to test whether recurring obligations and ordinary weekly spending appear in the right places. This is one of the less obvious advantages of a gradual setup: it separates a connection problem from a planning problem. If the transactions are correct but the plan feels unrealistic, the issue is probably the budget design, not the account feed.
Screenshots
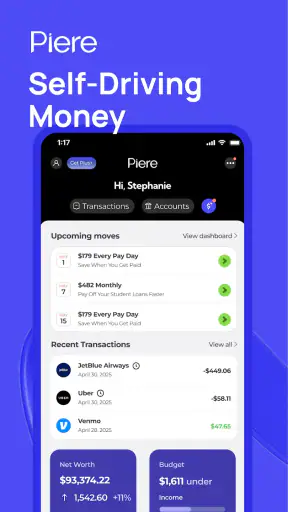
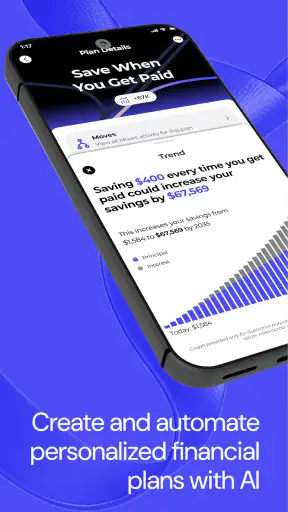
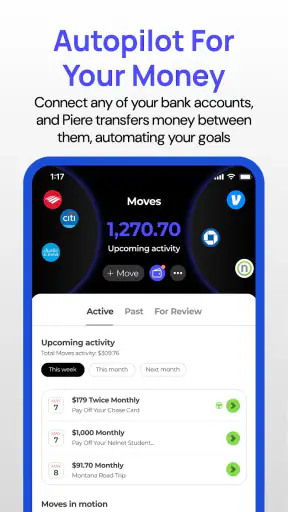
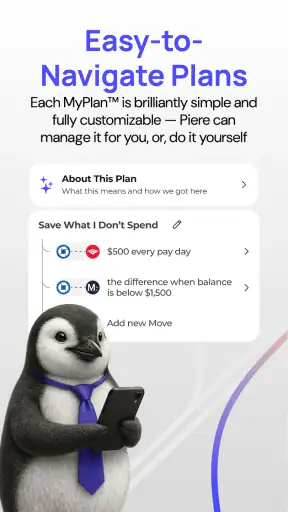
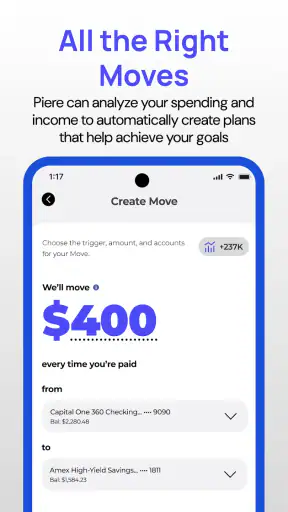
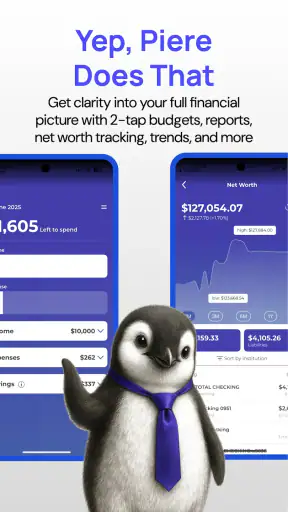
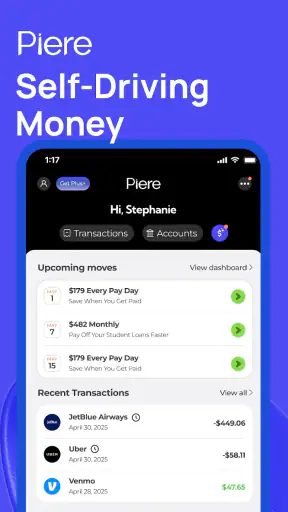
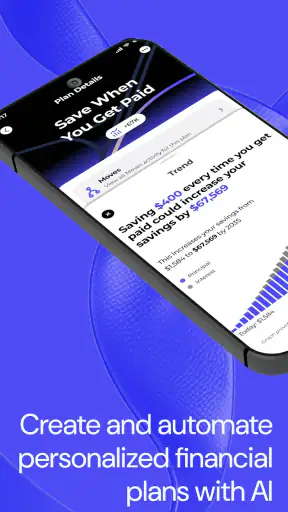
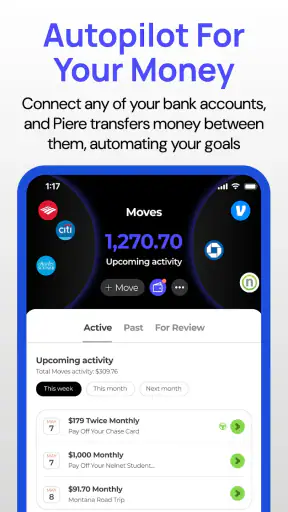
For saving goals, I would start with a target that has a clear purpose and a date I can realistically support. A goal for an annual bill, a small emergency reserve, or a planned purchase is easier to evaluate than a vague instruction to “save more.” I would also leave room for irregular costs. A plan that allocates every available dollar may look efficient, but it becomes fragile when a repair, seasonal bill, or medical expense appears.
Recovering when the workflow looks wrong
When something does not line up, I would troubleshoot in a fixed order. First, I would identify whether the problem is a missing transaction, an incorrect category, an outdated balance, or an unrealistic budget. Those are different problems and should not be treated as one general app failure.
For a wrong category, I would correct the transaction rather than rebuilding the entire plan. For an outdated balance, I would compare the timestamp and recent activity with the financial institution. For a missing item, I would check whether it is still pending or whether it belongs to another account. This sounds basic, but separating these cases prevents unnecessary resets and protects the useful history already built in the app.
If the connection needs attention, I would use the app’s normal account-management path, check that the login details are current, and try again only after confirming that the institution itself is available. I would not repeatedly enter credentials if the bank is asking for an extra security step or if its own service is having trouble. The safest recovery is a calm one: verify the source, wait for temporary processing issues, then reconnect once.
A particularly practical recovery method is to keep a short note of the last confirmed balance and the date I checked it. I would not store sensitive login information there. The note is simply a reference point, allowing me to tell whether the next update is genuinely new or merely displaying an older snapshot. This is helpful when several accounts update at different times.
I would also avoid deleting and recreating a budget as a first response. Starting over may remove the context that explains why a number changed. I would instead adjust one category, review the result, and then move to the next. Small changes make it easier to find the source of a mismatch and reduce the chance of accidentally hiding a recurring expense.
When the app is not the cause
Some frustrations originate outside the app. A bank may delay transaction information, mark a card payment as pending, change its sign-in process, or temporarily interrupt access. A phone’s operating system can also restrict background activity or behave differently after an update. In those situations, Piere may only be showing the information it can currently receive.
I would test this by checking the institution’s own app or website. If the transaction is absent there too, the budgeting app is unlikely to be the source of the problem. If the bank shows the item correctly while the budgeting view does not, then I would document the discrepancy with the account name, transaction date, and amount before seeking support. Clear details are much more useful than saying only that “the balance is wrong.”
There is another common misunderstanding: a budget is not the same as a bank authorization. Even if the plan says I have room in a category, the payment can still be declined because of a bank rule, a card limit, a merchant issue, or insufficient cleared funds. Conversely, a successful payment does not mean it belongs comfortably within the plan. I use the app for decisions and the financial institution for the final status of a payment.
Privacy and comfort are also valid reasons to stop. Someone who does not want to connect financial accounts may prefer a manual spreadsheet or a basic expense notebook. That option is slower, but it gives complete control over what is recorded. I would not recommend Piere to a person who will feel anxious every time a balance takes time to refresh or a transaction needs review.
Where it fits better than familiar alternatives
The usual alternatives each solve a different part of the problem. A spreadsheet offers flexibility and detailed formulas, but it depends on disciplined manual updates. A bank’s built-in spending view is convenient because it already knows the account, yet it may not provide the same deliberate planning habit across multiple financial relationships. A simple notes app is quick for reminders but weak for maintaining a coherent picture over time.
Piere sits between those choices. I would choose it over a spreadsheet when I want less manual copying and a more guided routine. I would choose it over a bank-only dashboard when my financial picture extends beyond one institution or when I want savings and spending decisions considered together. The trade-off is that convenience depends on connections and categorization behaving well, while a spreadsheet remains under my direct control.
For a couple or family, the app can be useful as a shared conversation starter, but I would not assume that a single view automatically resolves different spending habits. I would agree on category names and decide who checks unusual transactions. Without that small agreement, the tool can become another source of disagreement instead of a neutral planning aid.
For someone paid on an irregular schedule, I would use the plan conservatively. I would base essential commitments on dependable income and treat uncertain income as extra room rather than money already promised. This is a more suitable workflow than setting aggressive monthly targets that only work during a strong earning period.
Costs, expectations, and the right type of user
The app is free, but it includes optional in-app purchases ranging from one dollar and ninety-nine cents to seventy-nine dollars and ninety-nine cents per item. I would check the purchase screen carefully before confirming anything and decide whether the free experience already covers my needs. The presence of optional purchases is not automatically a problem, but it does mean I would avoid assuming every budgeting function is included without reviewing the available choices.
I think the best audience is a person who wants a more active money routine and is willing to review transactions when something looks unusual. It is also a good fit for someone moving away from scattered notes and trying to connect daily spending with savings intentions. The app becomes more valuable when I return to it consistently, make small corrections, and use the plan to guide choices before payday money disappears.
I would skip it if I only want a static calculator, a one-time debt estimate, or a completely offline ledger. I would also look elsewhere if detailed custom formulas are the main requirement. A spreadsheet can be better for highly specialized forecasting, while a bank’s own tools may be preferable for someone who wants the fewest possible connections.
In an ordinary scenario, I might check the plan before the weekend, notice that groceries and transport have already used more room than expected, and choose a cheaper activity rather than discovering the problem after the fact. Later, I would review the transaction categories and adjust the next week’s estimate. That loop—check, decide, review—is more realistic than expecting the app to make every financial choice automatically.
My practical verdict
After approaching it as a working budgeting companion, I see Piere as a sensible option for people who want planning and saving to become part of the same habit. Its value is not in displaying a balance by itself; it is in encouraging me to connect that balance with upcoming obligations and deliberate choices.
The setup deserves care. I would verify the operating system, compare initial account details, begin with essential categories, and avoid reacting to a delayed transaction by repeatedly resetting everything. When a number looks wrong, I would first determine whether the issue is categorization, timing, the connection, or the outside financial institution. Those checks make the experience calmer and produce a more trustworthy plan.
My recommendation is therefore positive but specific: try it if you want a connected finance workflow and are comfortable reviewing the information it presents. Keep a spreadsheet or manual method if you need total offline control, and use your bank’s own service whenever you need the definitive status of a payment. For the right user, the strongest benefit is turning vague financial intentions into a repeatable weekly decision process, rather than simply collecting another screen full of numbers.
Piere: Budget, Plan, Save FAQ
What is Piere: Budget, Plan, Save, and who is it designed for?
Piere: Budget, Plan, Save is a personal finance app designed to help users organize accounts, monitor spending, create budgets, and work toward savings goals from one place. It is especially useful for people who want a clearer overview of their finances without maintaining several spreadsheets. The app may suit beginners as well as users who already track money but want a more convenient mobile dashboard.
How does Piere connect to my bank and financial accounts?
The app generally works by allowing you to connect supported bank accounts, credit cards, and other financial services through a secure account-linking process. Once connected, transactions and balances can be displayed inside the app for easier tracking. Before downloading, check whether your financial institution is supported and review the provider’s privacy and security information, since availability and connection reliability can vary by country and bank.
Can I create budgets and track my spending automatically?
Yes, budgeting and spending analysis are among the app’s main purposes. After your accounts are connected, transactions can typically be organized into categories so you can see where your money goes and compare actual spending with your planned limits. Automatic categorization can save time, but it is still worth checking transactions occasionally because merchants may be assigned to an unexpected category or require manual correction.
Does Piere: Budget, Plan, Save help with savings goals and financial planning?
The app is intended to support more than simple expense tracking. You can use the available planning and savings features to set targets, monitor progress, and understand how current spending may affect future plans. Its usefulness depends on entering realistic goals and keeping connected accounts up to date. It should be viewed as a planning and organization tool, not as personalized investment, tax, or financial advice.
Is Piere: Budget, Plan, Save free, and is my financial information safe?
Pricing, available features, and subscription terms can change, so you should check the current listing in the Google Play Store or Apple App Store before installing. Some functions may require a paid plan or offer in-app purchases. Because the app handles sensitive financial information, read its privacy policy carefully and use a strong password, device security, and two-factor authentication when available. Never share banking credentials outside the official connection flow.











